
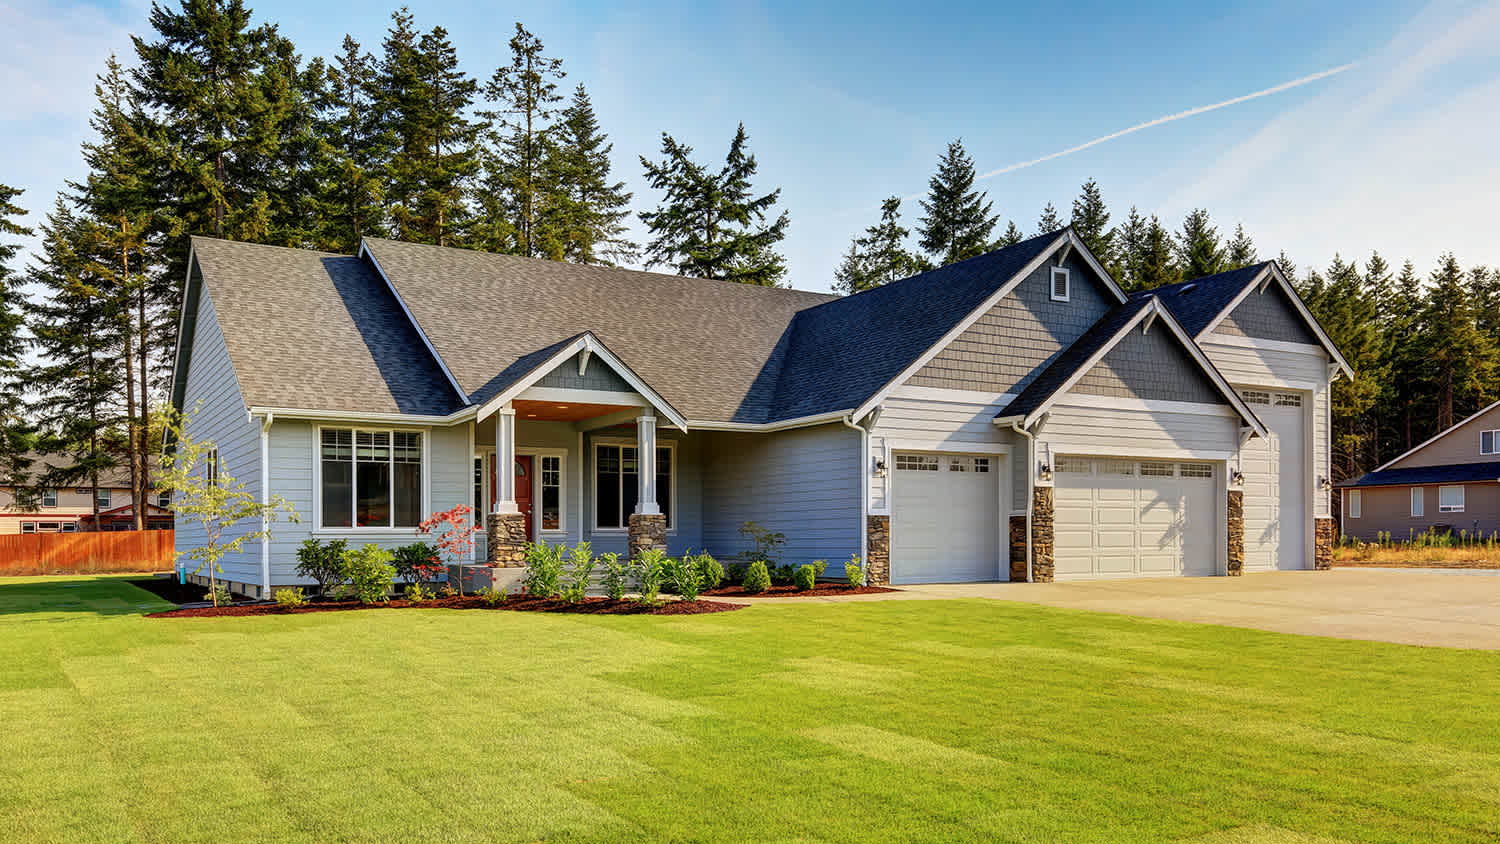
When you buy a home, you’ll likely need hazard insurance to protect it from things like natural disasters and burglaries. Learn how insurance costs can vary.
A new roof might lower your insurance premiums

Notifying your insurance company about a new roof can lower your homeowner's premium by 5% to 35%, depending on your roof materials and shape.
Your insurance discount depends on factors like roof shape, materials, impact resistance, and whether you pass a wind mitigation inspection in hurricane-prone areas.
You should contact your provider after installation with photo documentation, proof of licensed professional work, and warranty details to secure your discount.
Hiring a local roofing professional ensures your installation meets insurance requirements and provides the documentation needed to qualify for premium reductions.
If you are in the market for a new roof, we do not blame you for trying to cut costs where you can. Roof replacements—whether voluntary or involuntary—are expensive projects. Luckily, new roofs are among the various home improvement projects that can lower insurance.
If your roof qualifies for savings, you might see a reduction of 5% to 35% in your premium. But before you bank on an insurance discount for your new roof, know that several factors come into play, and discounts are not guaranteed.
Each company uses its own proprietary method to calculate a homeowner’s insurance rate. But generally, insurance companies consider things like a home’s age, its location, the cost to rebuild, the roof’s condition, and your credit and claims history. Companies also consider other factors like any remodeling projects you have done, if you have a pool, and whether your home has a security system.
Does a new roof affect insurance rates? The short answer is yes. How much it will affect your insurance rates depends on many factors, including the company you are insured with.
There is a reason why the phrase “a roof over your head” is so popular. We need all the different parts of our homes, but the roof is extremely important in protecting everything else from damage. The newer your roof is, the better it will keep your home protected from the elements, including severe weather.
Over time, as your roof nears the end of its lifespan, your home can suffer serious, costly damage. For example, a leaky roof can cause structural issues, mold growth, damaged flooring, and more. Additionally, an older roof is susceptible to issues like roof collapse in the case of excessive ice or snow buildup.
For these reasons, insurance companies consider the age and condition of your roof when determining your homeowner’s insurance rate. Older roofs are a liability, whereas new roofs provide security for your home. As you shop around for insurance, you may find some companies decline coverage if your roof is 20 years or older.
| What’s Typically Covered | What’s Typically Not Covered |
|---|---|
| Accidental damage | Damage due to poor maintenance |
| Nature-related damage | Cosmetic repairs |
| Roofs less than 10 years old | Roofs 20 years or older |
Now you may be wondering, “How much will a new roof lower my homeowner’s insurance?” A new roof does not automatically guarantee lower premiums. If getting an insurance discount for a new roof is your goal, you should first go over your plans with the insurance provider to see if a discount is possible. Roof type, the materials used, and whether your new shelter meets certain criteria will determine your new rate.
The shape of your roof will affect your homeowner’s insurance costs. For example, homeowners in areas prone to hurricanes or high winds have a better chance of securing a discount if they choose a hip-style roof. These have four sides and are typically the most costly to build. That said, insurance companies appreciate hip roofs with 30-degree angles because they fare best in hurricane weather.
Gable roofs look like an upside-down V, making them vulnerable to high winds. These roofs may cost more to insure.
Flat roofs are less common because water can pool on the flat surface and cause damage, which worries insurance companies. Flat roofs also have the shortest lifespan.

Some materials withstand environmental impact better than others, so the materials you choose can drastically change your insurance costs. Roofs with the lowest premiums are asphalt, slate, metal, and concrete. Wooden roofs cost about $150 more per year to insure than other types of roofs.
Wood: Least fire resistant and might require added fire protection for coverage. In areas with high risk of wildfires, providers may refuse to insure a wooden roof.
Asphalt shingles: Affordable and can be installed on top of an existing roof, but susceptible to decay, rot, and removal.
Slate: Low maintenance and resistant to high winds, fire, insects, and rot. Also heavy, susceptible to hail damage, and expensive. High replacement costs could increase insurance premiums.
Metal: Very durable and resistant to fire, rot, and insects. Reflects sunlight but dents easily from hail. Can be costly to install.
Concrete: Protects against hail, high winds, and heavy rainstorms.
If inspectors certify your roof as “impact-resistant”, you may get a discount through your provider in some states. Eligible roofing materials must meet Underwriters Laboratories or the Insurance Institute for Business and Home Safety’s Class 1 through 4 standards. Note that shingles with Class 4 ratings—the highest in the business—are usually 30% to 50% heavier, so it is important to ensure your home can handle the extra weight.
If your home is in a state susceptible to hurricanes—such as Florida, South Carolina, or North Carolina—you could save hundreds of dollars on your homeowner’s insurance by passing a wind mitigation inspection. An inspector will inspect the roof, but also consider windows and doors. To pass the test, your inspector will examine:
Roof seals
How the roof attaches to the home, specifically the nails and connectors
Specific coding requirements
If your roof has Secondary Water Resistance (SWR) or a Sealed Roof Deck, you may qualify for bigger discounts. Qualifying SWRs are underlayments applied to the sheathing or foam adhesive, and do not include standard underlayments or hot-mopped felts.
You might think that any significant home upgrade, including a new roof, will lower your insurance. But before asking, “Will a new roof lower my homeowners insurance?”, you need to know how insurers review claims—and your timing makes the biggest difference.
In general, you need to upgrade or replace your roof voluntarily to be eligible for lower insurance premiums. Most companies will award a discount as a thank you for improving your home’s quality and prioritizing safety. But if you need a new roof due to a disaster—or after a mandatory inspection—a roof replacement could actually increase your rates.
Consider how many claims you have made on your existing roof, as multiple insurance claims can hike premiums. If your roof replacement follows a partial repair after last year’s hurricane damage, be prepared for a possible increase, not a decrease.
Newer roofs can warrant better insurance rates because they offer better protection for your home against extreme weather. New roofs also have lower risk of mold, leaks, or pest problems. For this reason, some companies provide a “roof age discount.” If, however, your roof is over 20 years old, many providers consider it a liability. You may have difficulty finding someone willing to insure a roof that is more likely to require replacement soon.
Yes, you should let your provider know about a new roof. There is a chance that they may offer a discount on your premium, which could help offset the cost of your new roof. Also, if your roof happens to get damaged in the future, your insurance company will want to know how old your roof is.
After you give the company a call, mark down on a calendar all of the future maintenance tasks you are planning to do. Doing an annual roof inspection and cleaning it regularly will help your roof last as long as possible.
Upon installing or upgrading your roof, contact your insurance provider to inform them. You will have to provide new photo documentation, which is an important step to get all potential discounts. Be patient, as the approval process could take several weeks. In addition, your insurance provider might:
Request additional paperwork
Ask for clarification on detailed aspects of your claim
Inquire about your roof’s warranty
For the best chance at lower premiums, do not DIY this project. Hire a local certified and licensed roofer. The claim can be denied if you file a claim and cannot prove the work was done by a licensed professional. Of course, roofs with damages related to negligence will rarely meet discount criteria, so prioritize regular roof maintenance to keep it in the best shape possible, no matter how new your covering is.
If your roof is nearing the end of its lifespan, your homeowner’s insurance will not cover roof replacement costs. This is also true if you need to do any maintenance or upkeep for regular wear and tear. These are costs that the insurance company expects you to pay on your own; however, your insurance may pay for a new roof if yours was damaged accidentally or by nature-related events. Sometimes, your company will require that your roof is 10 years or newer for coverage to take effect.
The storm is over, but now you have to deal with a damaged roof. Knowing how to get insurance to pay for your roof replacement will be key to taking care of the problem quickly and efficiently. But first, you need to figure out if your insurance will cover storm damage. Check your policy and read all the fine print.
Generally, policies cover roof damage due to storms or damage from ice or snow buildup. If, however, your roof damage was due to flooding, high winds, or hail, your insurance may not cover you, depending on the coverage details.
Even if your roof damage is usually covered, you may not be eligible if your roof had prior damage that you did not fix, or if the damage is directly linked to poor maintenance.
Mitchell and the crew were top tier i am so happy with my new roof
 Home Genius Exteriors
D1 Roofing delivers outstanding service from beginning to end, backed by a strong warranty and expert teams. I highly recommend them for their excellence in meeting and surpassing expectations with unmatched communication. Choosing D1 Roofing was flawless decision
 Division 1 Roofing LLC
This place took $25,000 for a flat roof job with a five-year warranty and never returned to fix the leaks that were caused by their work. These people are not professionals and should not be doing this type of work. They incorrectly changed the pitch of the roof, and caused more damage than...
The technician was very professional and friendly. He answered all my questions and was very thorough. He left the fireplace area very clean . He inspected from the roof and advised me as to other work that might need to be done. There was no pressure there. I was very satisfied with the...
 Supreme brick & chimney
I am really impressed with their timeliness and turnaround. Mitchell came out, and we decided to move forward with their pricing. Our roof was on within a week, and we could not be happier with their team! Amazing company, great prices and honest, dependable craftsmanship. I highly recommend...
 Window Depot USA of Central Ohio
Manuel Calvillo is the best option in the area for roofing and you won't be disappointed.
They damaged multiple items on my property, including a marble slab used as a table top, tried to hide it, and refused to pay or replace. Arrived day one without a ladder to access roof & delayed a day. Left a mess in back yard; didn't wear face masks; no show by owner to property to see damages
 Grants Tree Service
I've hired Gary/Cherokee Roofing for two different homes, work quality, responsiveness, and completion have been great both times. And the prices quoted were very competitive. I would definitely hire again.
Lyle did a great job removing asbestos shingles from our front porch roof. They worked together with our roofer to make sure that the new roof was able to be installed on the same day that Lyle removed the asbestos shingles.
 Lyle Environmental
Bradley Builders did a good job replacing the roof on our front porch. They color-matched the existing shingles on the rest of the house and installed a metal ridge roll since we live in a historical neighborhood. They did the job while we were out of town. When we got back, everything was...
 Bradley Builders, Inc.
From average costs to expert advice, get all the answers you need to get your job done.
When you buy a home, you’ll likely need hazard insurance to protect it from things like natural disasters and burglaries. Learn how insurance costs can vary.
Insuring your home protects you financially and satisfies your mortgage. Learn how much homeowners insurance could cost you.
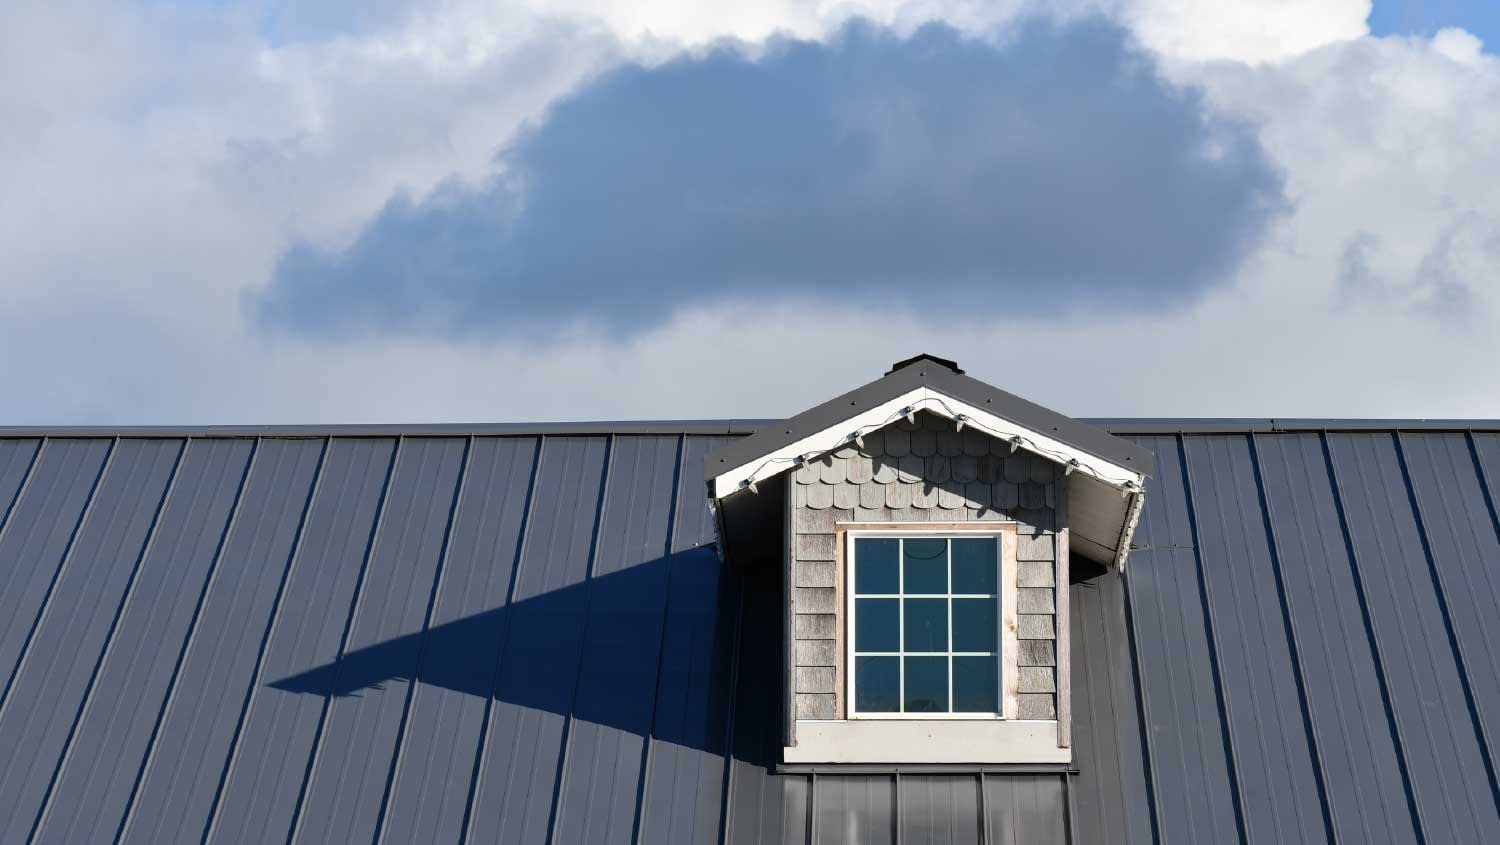
A metal roof protects your home from the elements and may even lower your insurance costs. Learn why installing a metal roof could save you money on insurance.
Dealing with insurance claims probably isn’t your favorite part of owning a home, but we’re here to guide you throughout the roof damage insurance claim process.
Not sure if you need to shoulder the financial burden of a new roof? Learn when insurance will pay for a new roof and when you need to cover the costs.
Curious if your home insurance covers roof leaks? Get the facts you need to know to protect your home and make informed insurance decisions.